Navigating the world of borrowing and lending can often feel like a complex puzzle, especially when you are responsible for managing financial obligations. Whether you are a business taking out a loan to expand operations or an individual with a significant personal note, understanding the exact breakdown of your payments is crucial. It is not just about knowing how much you owe, but also how each payment contributes to reducing your principal and covering interest.

This is where a well-structured amortization schedule becomes an indispensable tool. It offers a transparent roadmap of your debt, detailing every single payment from start to finish. For many, creating such a schedule from scratch can be daunting, requiring specific financial formulas and careful attention to detail. Thankfully, a reliable note payable amortization schedule template can simplify this process immensely, providing clarity and peace of mind for both lenders and borrowers alike.
Understanding the Core Components of a Note Payable Amortization Schedule
An amortization schedule serves as a detailed roadmap for any installment loan, including notes payable. It systematically breaks down each payment into its principal and interest components over the entire life of the loan. This level of detail is incredibly important because early payments on a loan often consist of a larger proportion of interest, with the principal portion gradually increasing as time goes on. Without an amortization schedule, it can be challenging to truly understand how quickly you are reducing your core debt.
For businesses, having a clear note payable amortization schedule is vital for accurate financial reporting and cash flow management. It allows companies to forecast their expenses precisely, ensuring that funds are allocated appropriately to meet their debt obligations. Individuals managing large personal loans, such as those for property or significant assets, also benefit immensely from this transparency. It empowers them to track their progress, plan for future financial goals, and even explore options for accelerating their debt repayment.
The beauty of a robust amortization schedule lies in its comprehensive nature. It doesn’t just show you what you pay; it shows you exactly *where* that money goes. This transparency helps in making informed financial decisions, whether it’s understanding the impact of an extra payment or simply budgeting effectively for future periods. It transforms a complex financial obligation into an easily digestible series of figures, making debt management significantly less intimidating.
Essential Elements of Your Amortization Schedule
- Original Loan Principal: This is the initial amount of money borrowed.
- Interest Rate: The annual percentage charged on the outstanding loan balance.
- Loan Term: The total duration over which the loan will be repaid, usually expressed in months or years.
- Payment Frequency: How often payments are made (e.g., monthly, quarterly, annually).
- Scheduled Payment Amount: The fixed amount you pay each period, calculated to fully repay the loan by the end of its term.
- Interest Paid Each Period: The portion of your scheduled payment that covers the interest accrued since the last payment.
- Principal Paid Each Period: The portion of your scheduled payment that directly reduces the outstanding loan balance.
- Remaining Balance: The outstanding amount of the loan after each payment is applied.
Creating and Utilizing Your Note Payable Amortization Schedule Template
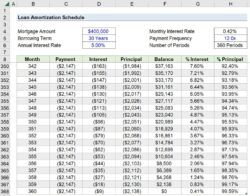
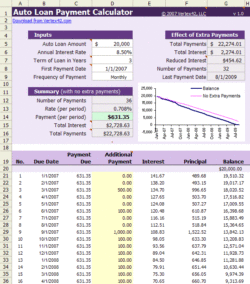
When it comes to managing your notes payable, having a reliable system is key. While you could technically calculate an amortization schedule manually, using a note payable amortization schedule template is a far more efficient and accurate approach. These templates are typically designed in spreadsheet software like Microsoft Excel or Google Sheets, pre-populated with formulas that automatically calculate the principal and interest components for each payment, along with the remaining balance, once you input your loan’s core details.
The process of using a template is straightforward: you simply enter the original loan amount, the annual interest rate, the loan term, and the payment frequency. The template then instantly populates the entire schedule, often displaying hundreds of rows if needed, each representing a single payment. This not only saves you countless hours of manual calculation but also drastically reduces the potential for human error, giving you confidence in the accuracy of your financial projections.
Beyond mere calculation, utilizing such a template provides unparalleled clarity for financial planning and analysis. For businesses, this means being able to present a clear picture of liabilities to investors, auditors, or internal stakeholders. For individuals, it offers a tangible way to visualize debt reduction, which can be incredibly motivating. You can easily see how much interest you will pay over the life of the loan and how much principal remains after any given payment.
Practical application of a note payable amortization schedule template extends to various scenarios. Imagine a small business that takes out a loan to purchase new equipment; with the template, they can accurately budget for each monthly payment and understand its impact on their cash flow. Similarly, if you have a personal loan from a friend or family member structured as a formal note payable, using a template ensures both parties have a clear, agreed-upon record of repayment, fostering trust and transparency.
Benefits of Using a Pre-Built Template
- Ensures accuracy in calculations: Eliminates manual errors with pre-programmed formulas.
- Saves significant time and effort: No need to build complex spreadsheets from scratch.
- Provides clear financial visibility: Easily track your principal and interest paid over time.
- Facilitates better budget planning: Forecast future payments and manage cash flow effectively.
- Simplifies year-end accounting and tax preparation: Provides organized data for financial statements.
- Helps identify potential errors in loan statements: Compare your schedule with lender statements.
Taking control of your financial obligations, particularly notes payable, begins with clarity and accurate information. A well-designed amortization schedule is the cornerstone of this clarity, providing a precise breakdown of every payment and its impact on your debt. It’s not just a tool for accountants; it’s an empowering resource for anyone managing a loan.
By leveraging a comprehensive note payable amortization schedule template, you gain a significant advantage in understanding, managing, and ultimately mastering your financial commitments. It offers a clear path forward, transforming what might seem like a daunting long-term debt into a manageable series of predictable steps, helping you make informed decisions and achieve your financial goals with greater confidence.