Navigating the world of loans can sometimes feel a bit like exploring a complex maze, especially when you encounter specialized options like interest-only loans. These financial products offer a unique structure that can be incredibly appealing for certain borrowers, providing lower initial payments by deferring principal repayment for a set period. However, understanding how these loans function throughout their entire term, particularly when the principal repayment phase begins, is absolutely crucial for sound financial planning.
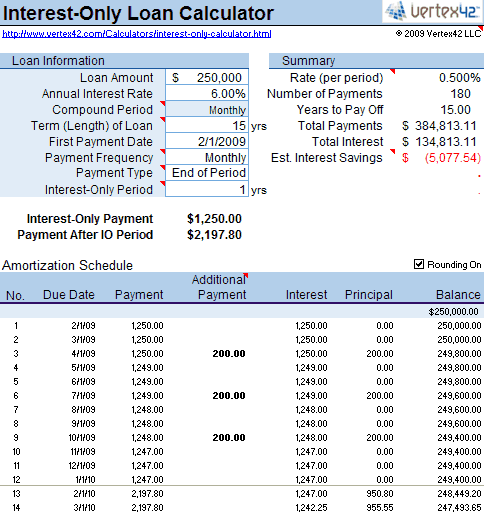
That’s where a clear, detailed interest only loan amortization schedule template becomes an indispensable tool. It transforms the abstract concept of your loan into a tangible, month-by-month breakdown, showing you exactly what to expect from your payments and how your loan balance will change over time. Far from being just a dry financial document, it’s a roadmap that helps you visualize your financial journey, manage your cash flow effectively, and make informed decisions about your future.
Understanding Interest-Only Loans and Their Payments
Interest-only loans are fascinating because they break away from the traditional loan structure where every payment includes both principal and interest from day one. Instead, for an initial period, your monthly payments are solely dedicated to covering the interest accrued on the outstanding loan balance. This design can significantly reduce your financial burden during the early stages of the loan, freeing up cash flow for other investments, business operations, or simply making the loan more affordable to start with. Imagine being able to purchase a home or fund a project with substantially lower monthly outgoings for the first few years.
However, it’s vital to remember that this reduced payment phase is temporary. The principal amount of your loan remains untouched during this period, meaning your overall debt doesn’t decrease. Once the interest-only period concludes, the loan transitions into a fully amortizing phase, where your payments will now cover both the remaining principal and the interest. This transition typically results in a noticeable increase in your monthly payment, as you’re now essentially catching up on the principal you haven’t been paying down.
For this reason, having a clear understanding of your loan’s structure from start to finish is paramount. Without a detailed schedule, it’s easy to be caught off guard by the payment jump. A comprehensive template helps you not only track the interest-only phase but also prepare for the shift, allowing you to budget effectively and avoid any financial surprises down the line. It offers transparency and predictability, which are key components of responsible financial management for any borrower considering this type of loan.
Key Components of an Interest-Only Payment Schedule
- Loan Amount The original principal borrowed.
- Interest Rate The annual percentage rate charged on the loan.
- Interest Only Period Duration The number of months or years where only interest is paid.
- Fully Amortizing Period The remaining loan term after the interest-only phase, where principal and interest are paid.
- Monthly Payment During Interest Only Phase This fixed payment only covers the interest.
- Monthly Payment During Amortizing Phase This higher payment covers both principal and interest.
- Remaining Principal After Interest Only Phase The full original principal amount if no additional principal payments were made.
- Total Interest Paid The cumulative interest paid over the entire life of the loan.
- Total Principal Paid The cumulative principal paid over the entire life of the loan.
Creating Your Own Interest Only Loan Amortization Schedule Template
Having your own interest only loan amortization schedule template is more than just a convenience; it’s a powerful financial planning tool. It allows you to model different scenarios, compare loan offers, and confidently project your future cash flow. Whether you are considering an interest-only mortgage, a business loan, or any other financing with this structure, building out a clear schedule ensures you remain in control and fully understand the implications of your borrowing decisions, both today and years down the road.
The beauty of creating your own template lies in its adaptability. You can use a spreadsheet program like Microsoft Excel or Google Sheets to set up a dynamic model. Start by inputting your basic loan details: the initial loan amount, the annual interest rate, and the total loan term. Then, clearly define the duration of your interest-only period. This foundational data will be the engine for calculating your payments and outstanding balances throughout the loan’s lifecycle.
For the interest-only phase, calculating the monthly payment is straightforward: it’s simply the monthly interest on the original loan balance. For example, if you have a 100,000 loan at a 5 percent annual interest rate, your monthly interest payment would be (100,000 multiplied by 0.05) divided by 12. During this phase, your principal balance will remain constant unless you choose to make additional principal payments. This flexibility to pay down principal early, even during the interest-only phase, is an important option many borrowers consider.
Once the interest-only period ends, your template needs to transition to a traditional amortization calculation. The remaining principal amount will then be amortized over the remaining loan term at the given interest rate. This will result in a new, higher monthly payment that includes both principal and interest. By meticulously charting each month’s payment, interest portion, principal portion, and outstanding balance, your interest only loan amortization schedule template provides a transparent view of your loan’s progression, empowering you with the knowledge to manage your finances effectively and prepare for every stage of your repayment journey.
Understanding the nuances of an interest-only loan and proactively planning for its various stages is a hallmark of intelligent financial management. A well-constructed amortization schedule is not merely a tool for calculation; it serves as a constant reminder of your financial commitments and helps you forecast your cash flow needs with precision. By taking the time to create and review this vital document, you equip yourself with the foresight needed to confidently navigate your loan and achieve your broader financial objectives.