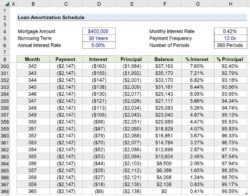
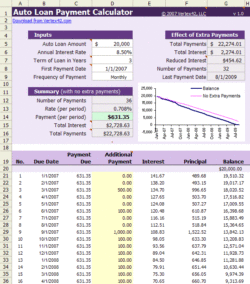
Managing your finances can feel like a juggling act, especially when you have multiple loans to keep track of. Whether it is a personal loan, a car loan, a mortgage, or student loans, staying organized is key to financial peace of mind. This is where a robust loan payment record template becomes incredibly valuable, serving as your personal financial assistant to ensure every payment is accounted for and your progress towards becoming debt-free is clear.

Without a clear system, it is easy to lose sight of due dates, forget how much principal you have paid down, or even miscalculate your remaining balance. This can lead to unnecessary stress, potential late fees, and a general feeling of being overwhelmed by your financial obligations. Many people rely on scattered notes, email confirmations, or simply hope for the best, but these methods often fall short when accuracy and consistency are paramount.
A well-structured template not only helps you avoid these common pitfalls but also empowers you to take proactive control of your financial journey. It transforms the daunting task of loan management into a streamlined process, providing a comprehensive overview of your debts and payments at a glance. Let’s dive into why such a tool is indispensable for anyone with financial commitments.
Why Tracking Your Loan Payments Matters More Than You Think
Keeping a meticulous record of your loan payments is far more than just good organizational practice; it is a critical component of sound financial management. It provides a clear, undeniable history of your transactions, which can be invaluable in numerous situations, from simple budgeting to complex financial disputes. Think of it as your personal auditor, always on guard to protect your financial interests.
One of the most immediate benefits is avoiding late fees and penalties. With a dedicated record, you can easily see upcoming due dates and ensure payments are made on time, every time. Late payments can quickly erode your budget and, perhaps more significantly, negatively impact your credit score, making future borrowing more expensive or even impossible.
Furthermore, a detailed payment history helps you understand the composition of your payments. For most amortizing loans, early payments consist of a larger proportion of interest than principal. Tracking this allows you to see how much of your hard-earned money is going towards the actual debt and how much is covering the cost of borrowing. This insight can even motivate you to make extra principal payments when possible, significantly shortening your loan term and reducing total interest paid.
In the unfortunate event of a discrepancy or dispute with a lender, your meticulously kept records are your best defense. Imagine receiving an erroneous late payment notice or a higher-than-expected balance statement. Without your own proof of payment dates and amounts, it can be incredibly challenging to argue your case. A comprehensive loan payment record template provides you with the undeniable evidence you need to resolve such issues swiftly and effectively.
Empowering Your Financial Planning
Beyond problem-solving, detailed loan tracking empowers your broader financial planning. By consistently monitoring your remaining balances and payment schedules, you can gain a clear picture of your overall debt burden. This knowledge is crucial for making informed decisions about saving, investing, and taking on new financial commitments. You can project future cash flow requirements and strategically plan for debt reduction or other financial goals.
It also fosters a greater sense of financial discipline and awareness. Regularly updating your payment records keeps you intimately connected with your financial situation. This hands-on approach can demystify your loans, making you feel more in control and less intimidated by the numbers. It transforms passive borrowing into active management.
Ultimately, a robust system for tracking your loan payments provides invaluable peace of mind. Knowing exactly where you stand with each loan, that every payment has been correctly recorded, and that you have a historical account of all transactions significantly reduces financial stress and allows you to focus on other aspects of your life with greater confidence.
What to Include in Your Loan Payment Record Template
To make your tracking truly effective, your loan payment record template should be comprehensive enough to capture all the essential details of each loan and every payment. A good template acts as a central hub for all your loan-related information, making it easy to reference, update, and analyze your progress over time. It should be designed for clarity and ease of use, ensuring you can quickly find the information you need without digging through piles of paperwork or digital files.
The beauty of a well-designed template is its ability to consolidate disparate pieces of information into one coherent view. Instead of logging into multiple lender portals or sifting through bank statements, you have a single source of truth. This centralized approach not only saves time but also reduces the likelihood of errors that can arise from inconsistent record-keeping across different platforms. Your template should be a dynamic document that grows with your loan journey.
Here are the key pieces of information that every effective loan payment record template should contain, ensuring you have a complete picture of your loan and its repayment:
- Loan Identification Number or Account Number: For easy reference with your lender.
- Lender Name and Contact Information: Essential for communication or inquiries.
- Original Loan Amount: The initial principal borrowed.
- Interest Rate: The annual interest rate applied to your loan.
- Loan Term: The original duration of the loan (e.g., 5 years, 30 years).
- Payment Due Date: The specific date each payment is expected.
- Scheduled Payment Amount: The regular amount you are required to pay.
- Date Paid: The actual date you made the payment.
- Payment Confirmation Number (if applicable): For digital payments.
- Principal Paid: The portion of your payment that reduces the loan balance.
- Interest Paid: The portion of your payment that covers the cost of borrowing.
- Remaining Balance: The outstanding amount after each payment.
- Notes Section: For any specific comments, like extra payments made, disputes, or special arrangements.
Having all these details organized in one accessible format simplifies the entire loan management process. It allows you to monitor not just if a payment was made, but how that payment impacts your overall debt, guiding your decisions and reinforcing your commitment to financial responsibility. This level of detail empowers you to negotiate with lenders, apply for refinancing, or simply understand your financial standing with unparalleled clarity.