Managing your finances can sometimes feel like juggling flaming torches while riding a unicycle – exhilarating but incredibly stressful if you drop something. Bills arrive from every direction, each with its own due date, and keeping track can quickly become overwhelming. It’s easy to miss a payment, incur a late fee, or simply feel anxious about whether you’ve got everything covered. This is a common struggle, and thankfully, there’s a straightforward solution that can bring order to the chaos.
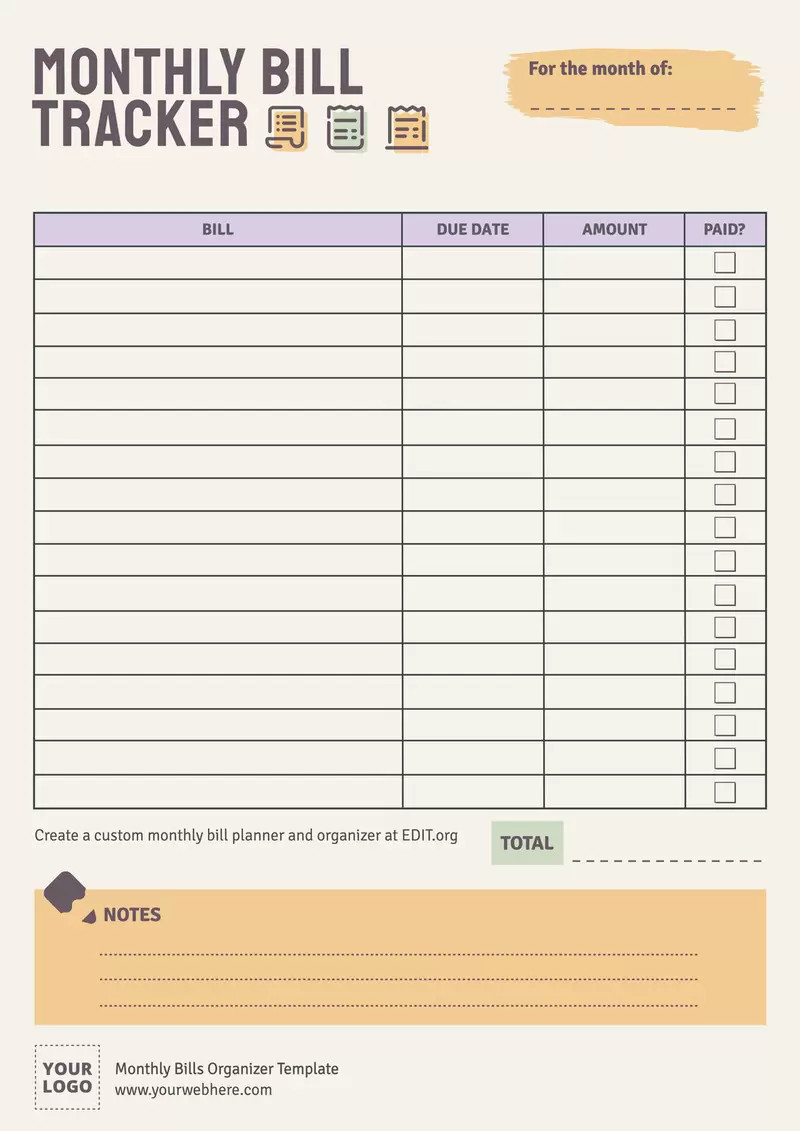
Imagine a world where you never have to scramble to remember if you paid the electricity bill, or if your internet provider is about to cut you off. That world is entirely possible with a little organization, and the right tool to help you stay on top of things. A reliable system can transform your financial life from a source of anxiety into a well-oiled machine, giving you peace of mind and more control over your hard-earned money.
Why a Monthly Bill Pay Schedule Template is Your Financial Lifeline
At the heart of stress-free bill management lies proactive planning, and that’s precisely where a robust monthly bill pay schedule template steps in. This isn’t just a simple checklist; it’s a comprehensive tool designed to give you a clear, consolidated view of all your financial obligations for the entire month. Think of it as your personal financial command center, allowing you to see exactly what needs to be paid, when, and how much, long before due dates even approach. The benefits extend far beyond merely avoiding late fees; they encompass better budgeting, improved credit health, and a significant reduction in financial anxiety.
By laying out all your bills on a structured template, you gain invaluable clarity. No more guessing games or frantic searches through email archives for payment reminders. You’ll know exactly what money is allocated for fixed expenses, making it easier to see how much is left for discretionary spending or savings. This transparency is crucial for making informed financial decisions and achieving your long-term goals, whether that’s saving for a down payment, a vacation, or simply building an emergency fund. It empowers you to budget more effectively and identify areas where you might be able to cut back or reallocate funds.
Key Components of an Effective Template
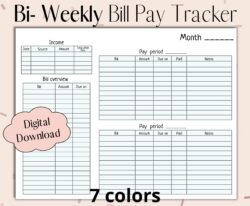
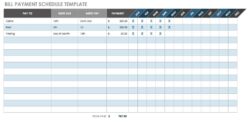
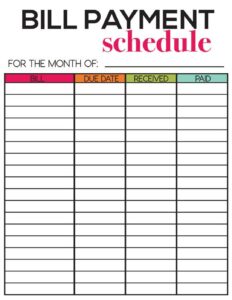
For a monthly bill pay schedule template to be truly effective, it needs to capture essential details that provide a complete picture of your financial responsibilities. While you can customize it to fit your unique needs, certain elements are universally helpful in ensuring no payment slips through the cracks. The more detailed you are, the less room there is for error or forgotten obligations.
* Biller Name (e.g., mortgage, car insurance, streaming services, credit cards)
* Due Date (the exact day payment is expected)
* Minimum Payment Due (if applicable)
* Actual Amount Paid (once payment is made)
* Payment Method (e.g., auto-pay, manual transfer, check)
* Payment Status (e.g., pending, paid, scheduled, overdue)
* Confirmation Number (a useful detail for any disputes or record-keeping)
* Notes/Remarks (for any special circumstances or reminders)
Having these fields laid out clearly helps you track each bill from its initial notification to its final payment, creating an undeniable paper trail that’s incredibly useful for auditing your finances or resolving any payment discrepancies.
Implementing Your Monthly Bill Pay Schedule Template for Success
Once you have your chosen monthly bill pay schedule template ready, the next step is to integrate it into your routine effectively. This isn’t just about filling in the blanks; it’s about establishing a consistent habit that transforms your approach to money management. Start by gathering all your recent bills, statements, and any recurring payment notifications. Populate the template with all your known expenses, ensuring accuracy down to the exact due dates and amounts. This initial setup might take a little time, but it’s an investment that pays dividends in peace of mind.
A key to successful implementation is choosing a regular “bill pay day” each month. This could be shortly after you receive a paycheck, or simply a day you designate specifically for financial administration. By dedicating a consistent time, you build a routine that makes bill paying less of a chore and more of an automatic, stress-free task. Use this time to update your template, review upcoming due dates, and schedule any manual payments. The goal is to move from reactive bill paying to proactive financial management.
To truly maximize the benefits of your template, consider how it integrates with other aspects of your financial life. For example, if you have irregular income, you might need to adjust your payment strategies or build up a larger buffer in your checking account. If you rely on automatic payments for many bills, your template can serve as a vital double-check to ensure those payments are indeed processed and to catch any unexpected changes in amounts or due dates. It’s a dynamic tool that should evolve with your financial situation.
Don’t be afraid to experiment with different formats until you find what works best for you. Some people prefer a digital spreadsheet for its flexibility and calculation capabilities, while others might find a printable template more tangible and easier to stick on a fridge or corkboard. What matters most is that you use it consistently and that it genuinely helps you feel more in control of your money. Regularly reviewing your progress and making adjustments will ensure your template remains an effective ally in your financial journey.
Embracing a structured approach to your monthly expenditures can dramatically reduce financial stress and free up mental energy for other areas of your life. By consistently using a well-designed schedule, you gain a clear overview of your commitments, empowering you to make smarter financial decisions and build a healthier relationship with your money. This simple act of organization can set you on a path to greater financial security and a calmer future.