Launching a new financial product in today’s fast-paced banking world is an exciting venture, full of potential for growth and innovation. Yet, with every new opportunity comes a corresponding set of challenges and risks. Banks are constantly striving to meet evolving customer demands and stay ahead of the curve, which often means venturing into uncharted territory.

Navigating this landscape successfully requires more than just a great idea; it demands a rigorous and systematic approach to understanding potential pitfalls. That’s precisely where a robust framework, such as a new bank product risk assessment template, becomes an indispensable tool. It helps institutions proactively identify, evaluate, and mitigate risks before they can impact the product’s success or the bank’s reputation.
Understanding the Landscape: Why a Template is Crucial
The financial services industry is in a constant state of flux, driven by technological advancements, shifting consumer expectations, and an ever-tightening regulatory environment. Banks face immense pressure to innovate, whether by introducing digital-only offerings, embedded finance solutions, or personalized lending products. While innovation is key to staying competitive, it inherently introduces new layers of complexity and potential exposure that traditional risk frameworks might not fully address.
Every new product brings its own unique set of risks. These aren’t limited to financial losses; they encompass a broad spectrum including compliance breaches, operational failures, technological vulnerabilities, and significant reputational damage. Imagine the fallout from a product launch that fails to comply with new data privacy regulations or one that exposes customer information due to unforeseen software glitches. The repercussions can be severe, impacting not just profitability but also trust and brand loyalty.
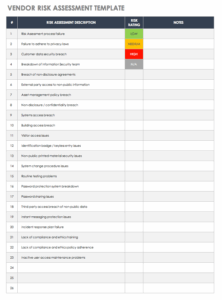
This is precisely why a new bank product risk assessment template is not merely a bureaucratic checkbox but a strategic necessity. It provides a structured, comprehensive framework for systematically dissecting every aspect of a proposed product. By standardizing the assessment process, banks ensure that no critical area is overlooked, promoting consistency and thoroughness across all new initiatives, regardless of their complexity or the team developing them.
Using a well-designed template allows banks to move beyond ad-hoc risk identification and towards a proactive, data-driven approach. It facilitates a holistic view, enabling stakeholders from various departments to contribute their expertise and collectively identify potential issues early in the product lifecycle. This early detection saves time, resources, and ultimately, helps in launching products that are not only innovative but also secure and compliant.
Essential Elements of Your Risk Assessment Template
- **Market and Strategic Risk:** How does the product fit into the bank’s overall strategy? What are the competitive pressures, and is there a viable market?
- **Regulatory and Compliance Risk:** Does the product adhere to all current and pending laws, regulations, and industry standards, including anti-money laundering (AML) and know-your-customer (KYC) requirements?
- **Operational Risk:** What are the process, system, and human resource impacts? Are there sufficient controls for processing, reporting, and customer service?
- **Technological and Cyber Risk:** Are the underlying IT systems secure, scalable, and resilient? What are the data privacy and cybersecurity implications?
- **Financial and Credit Risk:** What are the potential revenue, cost, and profitability projections? What is the credit exposure, if applicable, and how will it be managed?
- **Reputational Risk:** How might the public perceive the product? What are the potential impacts on the bank’s brand image and customer trust?
Building Your Robust Risk Assessment Process
Having a new bank product risk assessment template is the first step, but its true power lies in its implementation. The process isn’t a one-off event; it’s an integrated cycle woven into the fabric of product development, ensuring that risk considerations are front and center from conception to launch and beyond. This involves creating clear workflows, assigning responsibilities, and fostering a culture where risk awareness is paramount.
The assessment typically begins with an initial screening, often using a simplified version of the template, to quickly gauge the potential risk profile of a new idea. Ideas deemed viable then move into a more detailed analysis, where the comprehensive template guides a deep dive into each risk category. This phase requires thorough data gathering, scenario planning, and a critical evaluation of potential mitigation strategies. It’s about asking tough questions and seeking robust answers before significant resources are committed.
Effective risk assessment is a collaborative sport. It demands input from a diverse group of experts across the bank. Product development teams bring their vision, legal and compliance teams ensure adherence to regulations, IT specialists assess technological feasibility and security, operations teams evaluate process impacts, and financial analysts scrutinize profitability. This cross-functional dialogue ensures that all angles are considered and that risks are identified from multiple perspectives, preventing blind spots.
Furthermore, the world of banking risks is dynamic. What might be a minor risk today could escalate quickly due to market shifts, new regulations, or emerging cyber threats. Therefore, a robust risk assessment process doesn’t end at product launch. It includes continuous monitoring, periodic reviews, and the flexibility to adapt the new bank product risk assessment template itself as the risk landscape evolves. Regular updates and reassessments are crucial to maintaining the product’s safety and soundness throughout its lifecycle.
Here’s how to effectively integrate your template:
- **Define Clear Ownership:** Assign a risk lead for each new product initiative to guide the assessment process.
- **Establish Workflow Stages:** Outline distinct phases for risk identification, analysis, evaluation, mitigation planning, and approval.
- **Integrate with Product Lifecycle:** Ensure the template is used at key gates within the product development process, not just at the end.
- **Document Everything:** Maintain thorough records of identified risks, assessment findings, mitigation plans, and responsible parties.
- **Train Your Teams:** Educate product development, compliance, and other relevant teams on how to use the template and the importance of proactive risk management.
- **Regular Review and Update:** Periodically review the template itself to ensure it remains relevant and comprehensive in addressing new and evolving risks.
In the complex and competitive world of financial services, successfully launching new products is about striking a delicate balance between innovation and prudence. By embracing a structured approach to risk management, banks can not only protect their assets and reputation but also build a foundation for sustainable growth. It empowers teams to confidently explore new opportunities, knowing that potential challenges have been thoroughly considered and addressed.
Ultimately, a proactive stance on risk isn’t a barrier to progress; it’s an enabler. It allows financial institutions to innovate responsibly, delivering value to customers while safeguarding their operations and ensuring long-term stability in a rapidly changing market. This disciplined approach ensures that every new offering contributes positively to the bank’s overall strength and strategic vision.