Taking out a personal loan can be a fantastic way to bridge a financial gap, consolidate debt, or fund a significant purchase. Whether it is for home improvements, a wedding, or an unexpected expense, these loans offer flexibility. However, the true benefit and peace of mind from a personal loan come not just from receiving the funds, but from managing the repayment process effectively and without stress.

That is where a clear and organized approach to your finances becomes invaluable. Understanding exactly when and how much you need to pay, and seeing how those payments chip away at your principal and interest, can transform a potentially overwhelming obligation into a manageable task. A well-structured plan is the key to staying on track and avoiding any late fees or financial surprises down the line.
Why a Repayment Schedule is Your Financial North Star
Navigating the waters of loan repayment can feel daunting without a clear map. A comprehensive repayment schedule acts as your financial north star, guiding you through each payment period. It removes the guesswork and provides a transparent view of your financial commitments, which is essential for maintaining a healthy budget and preventing any missed payments. You will know exactly what is due, when it is due, and how each payment contributes to reducing your outstanding balance.
This clarity is not just about avoiding penalties; it is about empowering you. When you have a clear schedule, you can integrate your loan payments seamlessly into your monthly or bi-weekly budget. This foresight allows you to allocate funds appropriately, ensuring that other financial obligations are met while steadily progressing towards becoming debt-free. It turns a large, abstract debt into a series of smaller, achievable steps.
Furthermore, a detailed schedule helps you understand the anatomy of each payment. You can see how much of your money is going towards the interest and how much is chipping away at the principal loan amount. Especially in the early stages of a loan, a larger portion often covers interest, but as time progresses, more of your payment starts reducing the principal. This insight is not only educational but also motivating, as you watch your debt shrink over time.
Ultimately, having a solid repayment plan fosters a sense of control and reduces financial anxiety. It allows you to anticipate future payments, plan for them, and even explore options like making extra payments if your financial situation allows, knowing exactly how that might accelerate your debt repayment journey. It is a proactive step towards greater financial stability and peace of mind.
Essential Elements for Your Schedule
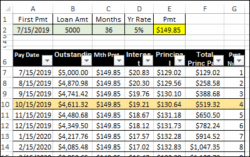
To build an effective personal loan repayment schedule template, you will need to include several key pieces of information:
- Initial Loan Amount: The total sum you borrowed.
- Annual Interest Rate: The percentage charged on your loan.
- Loan Term: The duration over which you agreed to repay the loan, typically in months.
- Payment Frequency: How often you make payments (e.g., monthly, bi-weekly).
- Start Date: The date your first payment is due.
- Payment Due Date: The specific date each payment is expected.
- Payment Number: A sequential number for each payment.
- Payment Amount: The fixed amount you pay each period.
- Interest Paid: The portion of the payment that covers interest for that period.
- Principal Paid: The portion of the payment that reduces your outstanding loan balance.
- Remaining Balance: The amount you still owe after each payment.
Building Your Own Personal Loan Repayment Schedule Template
Crafting your own personal loan repayment schedule template does not require advanced financial wizardry. You can use simple tools like a spreadsheet program, a free online calculator, or even just pen and paper if you are comfortable with basic arithmetic. The goal is to create a clear, actionable document that you can refer to regularly, ensuring you never miss a beat in your repayment journey. Start by gathering all the essential information from your loan agreement, such as the initial loan amount, the interest rate, and the loan term.
Once you have your loan details, begin by setting up the columns for your template based on the essential elements mentioned earlier. The most straightforward approach involves listing each payment period sequentially. For each period, you will calculate the interest portion of your payment first. This is typically done by multiplying your current outstanding balance by your interest rate (adjusted for the payment frequency, e.g., divided by 12 for monthly payments).
After determining the interest paid for that period, subtract it from your fixed payment amount to find out how much principal you are paying down. This principal payment then reduces your remaining loan balance for the next period. Repeating this calculation for each payment period will gradually show you how your balance decreases until it reaches zero at the end of your loan term. This process, known as amortization, gives you a clear visual of your progress.
Remember, the beauty of a personal loan repayment schedule template is its ability to be customized to your needs. You can add extra columns for notes, track actual payment dates, or even include a column for any additional principal payments you might make. Regularly reviewing and updating your template will not only keep you informed but also motivated, as you watch your loan balance steadily diminish month after month. It is a powerful tool for taking charge of your financial future.
Embracing the structure of a well-defined repayment plan truly transforms the loan experience from a potential source of stress into a manageable and even empowering journey. By meticulously tracking your payments and understanding their impact, you gain unparalleled clarity over your financial commitments. This proactive approach ensures you remain in control, consistently making informed decisions that align with your broader financial goals.
Ultimately, a structured repayment schedule is more than just a list of numbers; it is a commitment to financial responsibility and a testament to your ability to manage your money effectively. It paves the way for a future where you are debt-free, allowing you to allocate your resources towards saving, investing, and achieving the financial milestones that truly matter to you.