Navigating the complex world of finance today demands more than just smart business decisions; it requires a robust understanding and proactive management of risks. For banks, this isn’t just good practice—it’s an absolute necessity for stability, regulatory compliance, and ultimately, sustained growth. We live in an era where financial institutions face an ever-evolving landscape of potential threats, from cyberattacks and market volatility to credit defaults and regulatory changes, making a systematic approach to identifying and mitigating these dangers paramount.
That’s precisely where an effective enterprise risk assessment framework comes into play. It provides a structured way to look at the entire organization, pinpointing vulnerabilities before they escalate into major problems. Rather than reacting to crises, banks can anticipate them, allocate resources wisely, and build resilience. This holistic view ensures that no stone is left unturned, giving leadership the confidence that they have a comprehensive understanding of their risk exposure across all departments and operations.
Understanding the Core of Enterprise Risk Management in Banking
Enterprise Risk Management, or ERM, in the banking sector is about looking at risk from a top-down, holistic perspective, rather than in isolated silos. It’s a continuous, cyclical process of identifying, assessing, measuring, monitoring, and controlling all types of risks that could impact a bank’s ability to achieve its strategic objectives. Think of it as a comprehensive radar system designed to detect any potential storms on the horizon, allowing the bank to adjust its course or prepare for impact well in advance. This integrated approach ensures that decisions made in one department consider their ripple effects across the entire institution.
Without a well-defined ERM framework, banks risk operating with blind spots, potentially exposing themselves to unforeseen losses or regulatory penalties. The sheer volume and complexity of banking operations mean that risks are intertwined; a credit decision, for example, can have implications for liquidity, capital adequacy, and even reputational standing. Therefore, an effective ERM strategy not only identifies individual risks but also understands their interdependencies and aggregate impact.
Implementing a strong ERM culture means embedding risk awareness into every level of the organization, from the board of directors down to front-line staff. It encourages everyone to think about potential pitfalls and opportunities in their daily work. This proactive mindset transforms risk from something to be feared into a strategic tool that informs decision-making and helps the bank seize new opportunities with measured confidence.
To truly operationalize this, a tangible tool is often needed. This is where a well-structured bank enterprise risk assessment template becomes invaluable. It provides a consistent methodology for gathering risk data, evaluating its severity, and planning mitigation strategies across different business units. It acts as the backbone of the ERM process, ensuring that the bank’s risk profile is always current and accurately reflects its operating environment.
Key Components of a Robust Bank Enterprise Risk Assessment Template
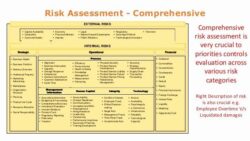
A comprehensive bank enterprise risk assessment template will typically cover a broad spectrum of risk categories, each requiring detailed scrutiny. These components ensure a thorough examination of all potential threats and vulnerabilities that a financial institution might face. By systematically addressing each area, banks can build a resilient defense against various adverse events.
Here are some of the critical elements you would expect to find:
- Operational Risks: These encompass risks arising from inadequate or failed internal processes, people, and systems, or from external events. This could include fraud, system failures, human error, or process breakdowns.
- Credit Risks: The risk of a borrower defaulting on their loans or other contractual obligations. This is often the largest risk category for most banks and requires meticulous assessment of individual and portfolio-level exposures.
- Market Risks: Risks associated with movements in market prices, such as interest rates, foreign exchange rates, equity prices, and commodity prices, which can affect the value of a bank’s investments and assets.
- Liquidity Risks: The risk that a bank will be unable to meet its financial obligations as they fall due without incurring unacceptable losses. This relates to the bank’s ability to fund its assets and meet its obligations.
- Compliance and Regulatory Risks: The risk of legal or regulatory sanctions, material financial loss, or damage to reputation that a bank may suffer as a result of its failure to comply with laws, regulations, rules, and standards of conduct.
- Strategic Risks: Risks associated with adverse business decisions, improper implementation of decisions, or lack of responsiveness to changes in the business environment. This category often ties into the bank’s overall business model and competitive landscape.
- Reputational Risks: The risk of damage to a bank’s reputation, which could lead to a loss of customer trust, reduced business, or legal and regulatory actions. This can often be an outcome of failures in other risk categories.
Developing and Implementing Your Effective Risk Assessment Framework
Creating an effective risk assessment framework requires more than just filling out a form; it’s about embedding a structured, adaptable process into your bank’s operations. The initial step involves clearly defining the scope of your assessment, understanding which business units, products, and processes will be included. This foundational work ensures that your efforts are focused and that the bank enterprise risk assessment template you utilize is tailored to your specific organizational structure and risk appetite. It’s not a one-size-fits-all solution, but rather a dynamic tool that evolves with your institution.
Once the scope is clear, the identification phase begins. This involves brainstorming potential risks across all categories, often facilitated by workshops with key stakeholders from various departments. Engaging a diverse group helps uncover risks that might otherwise be overlooked, given their unique perspectives on day-to-day operations and strategic objectives. This collaborative approach fosters a sense of ownership over the risk management process, making it more effective and sustainable.
Following identification, risks are assessed based on their likelihood and potential impact. This typically involves a qualitative or quantitative scoring system, which allows for prioritization. Not all risks are created equal, and some will naturally demand more immediate attention and resources than others. This systematic evaluation helps allocate resources efficiently, focusing on the most critical threats first, and providing a clear rationale for mitigation strategies.
Finally, the framework necessitates the development of clear mitigation strategies for each identified and prioritized risk. These strategies could involve avoiding the risk entirely, reducing its likelihood or impact, transferring it through insurance or hedging, or simply accepting it if the cost of mitigation outweighs the potential loss. Crucially, the process doesn’t end here; an effective framework includes continuous monitoring and regular review to ensure that the risk profile remains current and that mitigation efforts are still effective in a changing environment.
Adopting a robust approach to enterprise risk management is no longer optional for financial institutions; it is a fundamental pillar of sound governance and operational resilience. By systematically identifying, assessing, and mitigating potential threats, banks can safeguard their assets, maintain trust with their customers and regulators, and ultimately foster a more secure and prosperous financial future. This strategic outlook allows institutions to not only navigate challenges but also to confidently pursue growth opportunities in an increasingly dynamic marketplace.